


AI’s Real Impact in Telecom: Five Takeaways
A recent TelecomTV panel offered a grounded perspective to the AI conversation in the telecom industry. While industry optimism is high, the discussion among the speakers revealed a more nuanced reality. As they agreed, progress is real but uneven, and the biggest opportunities may not look like what many expect.
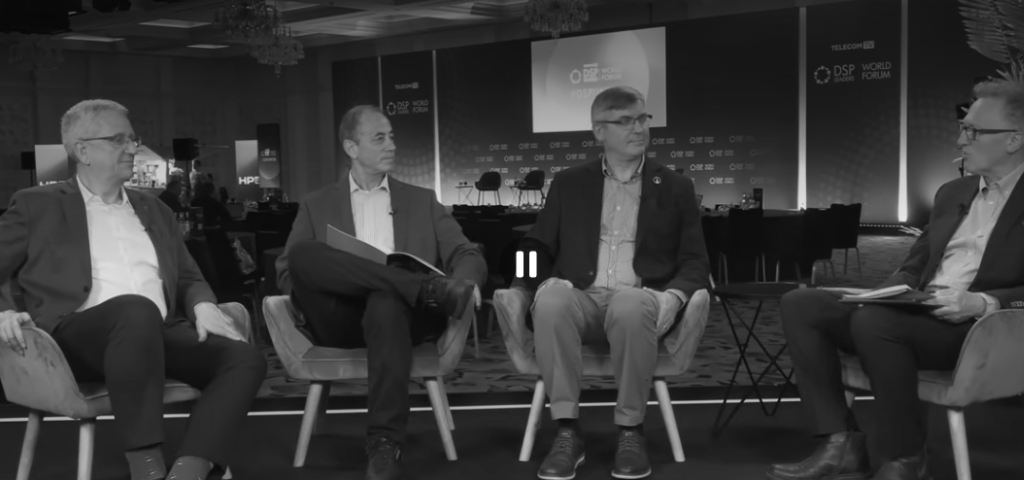
The panelists — Warren Bayek, vice president, Intelligent Edge, Software and Services, Aptiv; Robert Curran, consulting analyst, Appledore Research; and Diego R. Lopez, senior technology expert and chair of ETSI ZSM ISG, NOC of ETSI ISG NFV, Telefónica — repeatedly returned to questions of trust, operational risk, sovereignty, edge deployment, and realistic monetization.
Here are five big takeaways from the discussion.
1. Agentic AI is moving quickly, but production scale will require trust
The panelists agreed that AI is already delivering value, but it is accomplishing that primarily through established approaches such as machine learning, anomaly detection, predictive maintenance, and customer support automation.
In their views, that’s distinguished from agentic AI, which remains immature for mission-critical telecom environments. As Lopez argued, agentic AI remains too closed and vendor-centric for heterogeneous telecom infrastructures.
Operational trust is the primary barrier, said Bayek, noting that telcos have pursued closed-loop automation for decades but remain reluctant to hand control of critical services to autonomous systems.
Instead, the real opportunity is cross-domain automation, suggested Curran, where AI coordinates across multiple operational silos. Using AI-driven network automation and agentic operations is not a minor advantage. It has a direct impact on OpEx, workforce productivity, customer experience, and autonomous networks, and thus nearly every major operator is pursuing this.
These speakers are not alone in their opinions, based on current industry activity. GSMA, TM Forum, Microsoft, and major operators are now focused on developing standards, architectures, governance frameworks, and interoperable agent ecosystems because the technology challenge is increasingly becoming a trust and governance challenge.
2. The biggest AI opportunity may not be AI applications
One thought-provoking point came from Lopez and Bayek, who argued that telcos are unlikely to become major AI model providers. Instead, they see operators continuing their role as trusted infrastructure providers and data intermediaries, while adding new value creation as AI hosting platforms and broader ecosystem enablers.
Lopez described telcos as a potential “substrate” for AI, analogous to their role in IoT, while Bayek argued that operators possess unique assets: distributed infrastructure, regulatory expertise, secure environments, and operational trust.
This is a subtle but important shift. Rather than competing with hyperscalers or AI model providers, telecom operators may capture value by enabling AI services closer to users and enterprises.
3. AI revenue remains unproven, but the industry is becoming more ambitious
Curran warned that telecom has heard similar promises before around 5G and suggested that some AI benefits may come from reducing churn or preventing revenue losses rather than creating entirely new businesses. However, the panel also highlighted emerging opportunities in AI hosting, AI infrastructure services, data services, GPU capacity, edge inferencing, and enterprise AI platforms. Finding use cases takes time, as does ensuring the infrastructure exists to support it, but AI is already making an impact in areas such as customer care, AIOps/network operations, predictive maintenance, and churn reduction.
Bayek was particularly optimistic that telcos can participate in “physical AI” and edge AI ecosystems rather than in the foundation model race.
This closely mirrors recent industry research from McKinsey showing operators shifting AI strategies from pure efficiency initiatives toward monetization through GPU as a Service, edge AI, APIs, and AI infrastructure offerings. Operators are increasingly trying to move beyond cost savings toward commercial AI offerings.
The longer-term opportunity goes beyond simply hosting AI workloads. As network and AI infrastructure converge, operators may increasingly use common distributed cloud and accelerated-compute infrastructure for RAN, network functions and AI workloads – creating new economics around assets that historically served only the network.
4. Sovereign AI may become a strategic necessity
This was arguably the panel’s most strategically important discussion. Curran reframed the AI factory debate by saying, “The key question is not about AI factories, it’s about sovereignty.”
As the panel discussed, governments and critical industries increasingly want AI systems that are locally controlled, legally compliant, resilient to geopolitical disruption, and operated within domestic jurisdictions. Rather than building hyperscale AI campuses, panelists favored smaller, highly targeted sovereign AI facilities optimized for regulated use cases and regional requirements.
This aligns strongly with emerging telecom industry thinking around sovereign clouds and AI, trusted AI infrastructure, and national digital resilience.
5. AI may give telecom edge computing a compelling business case
All three speakers argued that edge AI represents a natural fit for telecom operators. They already own distributed infrastructure, local facilities, network edge locations, and low-latency connectivity.
Potential applications include robotics, industrial automation, AI-driven operations, computer vision, security systems, and mission-critical enterprise services.
“Only telcos own the edge,” Bayek commented – not simply edge compute, but a distributed network footprint that combines connectivity, physical infrastructure, network intelligence, and proximity to users and devices.
Toward an AI-enabled future
Ultimately, the panel rejected the premise that telecom operators will win by building giant models or competing with hyperscalers. Instead, they argued that telcos’ unique value lies in trusted infrastructure, sovereign deployment, edge computing, operational expertise, and data mediation.
That view is increasingly consistent with broader industry thinking. Current telecom AI strategies are converging around three priorities:
- Use AI to automate and eventually autonomize network operations.
- Monetize edge and infrastructure assets for AI workloads.
- Provide sovereign, trusted AI environments for governments and enterprises.
Those themes emerged repeatedly in the panel and are precisely where industry investment and standards activity are heading today.
For full details, watch the panel discussion and consider downloading the full TelecomTV “Telcos & AI” report.
AI for telecoms builds on the cloud-native foundations operators have already established. Discover how Wind River helps service providers deploy scalable, intelligent infrastructure for telecommunications, automation, and future 6G networks by exploring how to enable Edge AI for telco RAN, core, IT, and enterprise.
Monetize 5G and accelerate cloud-native network transformation for vRAN, Open RAN, core, and IT with a distributed cloud Edge AI management platform with ease of deployment and operations at scale. Explore Wind River’s Cloud Platform for telecommunications.
Wind River Blog
The Wind River Blog is made up of a variety of voices: executives, technologists and industry enthusiasts. We hope to foster conversations and encourage the sharing of insights regarding the evolving landscape of intelligent, connected systems with our ecosystem of customers, partners and colleagues.
 Get our RSS feed